Showing posts with label property. Show all posts

Saturday, May 25, 2013

Investing on Foreign Land Conversion

Have you ever been approached by investment opportunity on a piece of land oversea ? It usually goes like this ...
Land is limited, population is growing.  So investing on land is a low risk high return opportunity;  Especially on an island . . . but why oversea and how its a better investment ?
  • more structure and well organized land & property legislation 
With better laws in foreign country, one can be more assured in his land investment is being protected in terms of benefits and interest safe guards compare to your own country which may otherwise affected by cronism or corruption.
  • steady and growing population - usually a developed nation
Here the demand is being taken care of.  If the people in your country is leaving the country, then there may not be any more demand to your land in future.
  • tax free or exemption
Normally a country would love some money coming in from oversea, hence they may offer attractive tax incentive.  So investing on land oversea could actually become cheaper than investing land in your own country.
  • Land Conversion
To make the return more attractive, land investment is usually tight to conversion.  For example, the land was initially for farming purpose.  But as population grows, the land is to be converted to residential area.  Once converted, the value of the land usually increase drastically.  However conversion like this requires expertise planning and professional services.
So should you invest into an opportunity like this ?  


Says there is an offer on a piece of land near London where this farmland will be converted into a residential area in the next 5 years.  The offer is GBP 13 to GBP 16 per square feet.  Assume the buying process is simple and legal where you only need to deal with a local public company approved by your local government.  Buying process is as simple as using your credit card and checks writing.  Total investment could be as small as 1,000 sq ft.

Will you buy into this offer ?  What are that factors that will affect your decisions ?

Sunday, September 12, 2010

21st century Economy Politic Quadrant


The Economy-Political Quadrant may seems like telling where to keep or invest your money despite good or bad time.


It indeed works very well during 20th century. Unfortunately comes to 21st century, not only has the year changed, personal finance arena has changed drastically as well.

Gold has been speculated so much that it MAY no longer be the standard of money.

There used to be only 'property' in the city. Now there are satellite towns, suburbs ... agriculture lands and even dust bins ( recycle ) have become valuable estates too. While property remains the right category to invest into whenever economy is booming, but predict the right future seems like tougher than buying lottery.

Government bonds used to be de-Facto action when a country is stable. But in today's world, a country is as smart as a taicon's finance. One day they are the LARGEST, the next day they are GONE.

Stock market used to be the back bone of a country's economy. However, the market of derivatives has become so HUGE that the REAL and PHYSICAL is NO LONGER more real than VIRTUAL

So in 21st century, the element of Stock-Property-Funds-Gold is really questionable. However, one fundamental that doesn't change is that

you will have to identify what to do at what time that is BEST for YOU !

Hope you will find your own very best Economy-Political Quadrant soon !


Wednesday, August 18, 2010

Economy Politic Finance Quadrant

There are 2 BIG main external factors affecting our investment decisions
  • Economy
  • Politic
When the time is really bad (economy downturn and politically unstable), its best to park your money under something that is really stable, ie Gold. Which is by definition usable anywhere you go in anytime.

When its good time, invest direct to the stock market would yield very good return.

When the economy is not so good in a strong country, the government bonds or related money market would be able to yield higher return than just gold.

However, the most dispute solution in good economy unstable country is investment in property. This is mainly due to easier rental and higher chance of capital gain.

By simply moving money around depends on the political and economy situation, one was able to achieve more than 12% compound return for the past 20 years. That is equivalent to a 10X return.

But by no mean this is easily done. Some of the concerns include;
  • how would one know exactly when economy/politic turns good/bad ?
  • is Gold the ONLY option ?
  • property may not easily liquidated
  • how to choose which property or stock market ?
. . . which can be explored further.

Sunday, June 27, 2010

Recession over, what's NeXT ?

Sometimes I feel very depress when my prediction comes TRUE.

For those who don't know yet, Malaysia is going through a transition where political power could potentially shared between 2 parties; instead of just one-side-say-it-all like the past 50 years. Unfortunately, the initial phase of this transition has ended in a way when our new Prime Minister has strategically resolved it.

At the moment New Economy Model was presented, I immediately sensed the game err they plan to play. Because exactly the same game plan has been played in USA before. While it is true that Malaysia CAN become a developed nation by adopting those moves but it has also been proven that such finance structure is NOT sustainable. Just see what has happened in USA and what is happening in Europe.

Although as if recession is over now, actual effective inflation experience the SHARPEST rise in last 2 months, as high as 25% to 50% if you visit hypermarket often. That is not the worst. What is happening now is that major manufacturers are deceiving consumers in large scale openly. While their products have inflated severely, they run advertisements and promotions as if their products are ON OFFER ! All these are done as part of the exercise to smoothen the transition into a developed nation, hence they have government support behind the scene at all cost. Ahem ... at consumer's cost that is. While these are nothing new to those who have seen it all, but sadly ... there are more consumers falling into it than realizing it at all.


As mentioned in what can we do when bully by the big boys, there is probably nothing much we can do to STOP anything now. So there are just a few things we can probably watch carefully and ride on so that we can get a piece of the pie too ...

  • Property will rise drastically. Wherever you are staying right now and despite how much you like it, it may become more worth while to sell it off in the next 10 years. So do plan ahead where you may want to stay 5-15 years later. This may become your LAST and ONLY ticket when the nation is developed and you are still under developing.

  • Double your salary in the next 2-3 years. If you wait till the wave carries you, you will always stay behind. You salary WILL increase AFTER the effect of inflation fully kick in. But by then, your increased salary will mean much less. So you really have to think for yourself now. If you are really royal to your employer, your employer should have seen this coming too and take care of you but did it ?
Other than that, derived finance products like futures, options and forex will over shine proper financial planning so much that a lot of weird and ad-hoc theories will surface out. Most people will no longer be able to differentiate what the real proper investment is. On the other hand, that is due to more and more improper investments will actually obtain real returns for the new few years. So if all you care is to get more money, then it should fine temporary.

Hence, MalPF only has one advice to all. Be deviated all you want, just remember to engage an exit strategy and keep yourself in high cash flow condition.

Tuesday, March 9, 2010

Do NOT Leverage EVERYTHING


There are certain fundamental stuffs that you should do even before you fully understand what they are. That will at least keep you afloat at a certain stage, also often used as resting stage or jumping stone to higher level. Usually this stage is also adequate for young adult to retire early. What goes beyond however will require clear target and solid methods. Some of the easier methods shared before are ;

One common element to do great thing is the use of Leverage. Unfortunately, a lot of people learn about leveraging before they learn the right method. As a result they simply leverage everything they had.

Leverage is basically maximizing result, no matter what direction it goes. If you have a good investment system, leveraging it would result a bigger profit. Likewise, if you have a bad or no system at all, leveraging on it would only give unknown result if not just worse.

Leverage amplifies both the rewards and the risks. Hence if the risk was not properly mitigated before hand, then the result is always disastrous.


Make sure you have found a good method that you like and have proven working well for you, ie. your cup of tea. Then only apply Leveraging technique on that particular system. Else just DON'T Leverage at all !


One of the most common wrongly leverage stories come from property investment.

Tuesday, February 2, 2010

Monopoly - Why NOT Property in PF ?


Monopoly is one of the most popular board games. When Charles lost his job, he played The Landlord's Game and then created his own version of the game which later became Monopoly. Originally he was trying to include all the dynamics of property investment into the game but as time goes people find those are too complicated. Hence today's Monopoly is simplified until its a 8 years old game. Now new board games are developed everyday by adding back those left out rules - including Robert's Rich Dad.

Some who followed this blog long enough may already know that Property Investment is NOT a suitable personal finance tool.

Although there are ways to obtain guarantee income through property investment at personal finance level, but those who have never done it would think such method is ridiculous, impossible and paper talk only. Then when they use other approaches, they miss interpret active income as passive income. As a result they would do great at times but when the big boys swing another direction, they may get knocked so hard that they not only fell off the chair but they may enter a never return land. Even at this 21st century, generally people are still NOT able to digest stuff like strategy cost, personal finance scoping etc. Hence its just too 'risky' for anyone to simply use property investment as their personal finance tool.

We may get some resonances from some of the important key concepts which are still in Monopoly :


"Your goal is not just to get rich, you HAVE TO Bankrupt everyone else !"

In 21st century personal finance, we want to revert the 20-80 rule. We want most of the people to achieve finance freedom without bringing harms to the others. We want MOST of us to get what we want, we no longer want to just follow the big boys just for the sake of it-used-to-be-like-that. We may want to be rich but we have no interest to bankrupt anyone else in the process.

The nature of property investment is an active income. So its really a business. In business world, we do have to limit the ability of our opponents in order to grow big, stay big and be successful. But in "personal" finance, we don't have to.

But guess what, "Banks never run out of Money, they just print on plain paper ... " So you will NEVER able to bankrupt banks and banks will always be the winner.


On the more positive side, such problems only exist if the play ground is limited. ie. There are only so many lands, so many buildings, 4 stations and 2 utilities companies in Monopoly. In real world, New play ground is created all the time. As long as there are more play grounds created than the number of bankrupts, theoretically people who went bankrupt at one game can simply jump to another new game and play again.

Now do you understand why governments all over the world are creating Mega Projects all the time ?

Although Charles started Monopoly but now his whole thing has been "monopolized" by Parkers Brother where Charles was only one of the developers and Parkers Brother is the official owner. So much about monopoly huh ?

Tuesday, January 19, 2010

Mortgage vs Loan


Very often the terms mortgage and home loan are used interchangeably. Although it might not cause big harms but understanding the difference may bring positive impact to your personal finance ie. in Property Investment.

In fact, mortgage is the opposite of loan.

When you need extra money, someone can lend you some and in return they gain profit when you repay them. The lender may ask for collateral like your house so that if you don't repay them, they can take possession of your house, sell it and still earn a profit by doing so. They give you a loan.

If you have something valuable and you want to exchange it temporary for some money, you can prove to people how valuable your possession is and why should they give you money for it. You get your money if the lenders are satisfied their interests will be taken care of. You have just mortgaged your belongings.

Loan is a lender's contract,
mortgage is a borrower's contract.

At one instance, it may seems the same. Its just a story told from different angles. But if you think for a moment as a borrower, do you want to follow your lender's contract or should you come up with your own's ?

If you start thinking the whole money borrowing thing from your own angle and for your own interest, you may just come up with some unique and interesting arrangements.

Items that can be mortgaged are not limited to your own properties. If you are holding some collaterals from other people, you can mortgage them to higher bidders.

You don't have to mortgage 100% of your property. Since it is really up to you, you can even split a single property to 4 different mortgages and borrow money from different sources. However, you would need some very good reasons why people still want to lend you the money. But if it is a 4 sections building, it wouldn't look that ridiculous anymore, would it ?

Item that can be mortgaged does not even need to be mortar. An idea or a method can be mortgaged too. As long as someone believe in your value judgement and their interests taken care of, they can lend you money. So you can literary mortgage your property for money without giving it out as a collateral at all. Especially applicable when you are earning revenue from such properties.

Loan or Mortgage ?
Borrower or Mortgagor ?
Lender or Mortgagee ?

As mentioned earlier, this is just a matter of how the story is told. Do you want others to control your story or do you want to tell your owns ?


Saturday, January 9, 2010

Some data on Malaysia Property

First of all, Malaysia property is one of the cheapest in the region ... so smaller foreign property investors ( less than 10 millions) who are interested in this region may be interested in us.

Our rent is also low ... so its rather easy to rent a place and start business here. So this means its rather easy to rent out your property ... especially if you explore with foreign business men.

The interesting part is our rental yield is quite high at 8.86%. This is actually common in developing countries. This ... however ... will go down in years to come.


This one is similar to rental yield but just shown in a reverse manner. This means you will get back your total investment rather fast in Malaysia.


The cost of both buying and selling is low too. But this usually subject to other terms and conditions like different fee imposed on different sale period.


In the past 5 years, Malaysia property has risen more than 14%

But the whole of last year is almost stagnant.

Thursday, January 7, 2010

New Sabah Property : HOT !


Famous Feng Shui sifu said that new sabah property is going to continue to be HOT for the next 20 years. As a matter of fact, he refers to both Sabah and Sarawak. Some may have already seen that properties development have been on the rise in East Malaysia for some time now especially in Kota Kinabalu, capital of Sabah.

Although there have been critics that such a trend has no sustainable growth and therefore they considered it a bubble rather than a living standard up scale.

However it doesn't really matter how right they may be or how noble you are, the market doesn't really care. If it continues to have more buyers than sellers then the price will continue to trend up, despite anything else i.e. no one actually utilize those properties.


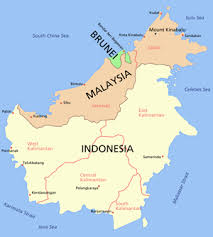
It shouldn't be too hard to understand the rise. First of all, Borneo is an island. Island has limited land. So 'eventually' the price of land will rise. Its been proven in Japan, Hong Kong Island, Singapore and even Australia ( a continent but nevertheless an island geographically). And its not just any island, its the 3rd largest island in the world. Imagine you can fit 1,000 Sinagpore in Borneo !!

But not all islands have great track record. The largest island in the world - Greenland - doesn't do so well, most of the very small one man islands do not do well neither. Is Borneo too big or could it be just nice ? New Guinea (2nd largest island) and Madagascar (4th) are both not that encouraging. The list continues down until Great Britain, the 8th largest island who obviously did pretty well in property growth. Limited land of an island may be a good starting point but other deciding factors seem to be more influential.


What other positive notes do we have ? Politics movement is good for Sabah property. As a matter of fact, due to Malaysia politics instability, the paying master political party has to move to East Malaysia. Whether or not you need houses, more will be built. How do they justify building more ? They will get buyers if you don't. Property trend is a developer's game. If they have the power to sustain selling price during bad time, the only thing left is up trend.

20 more years of HOT property growth is a surprisingly SHORT period given that it is a land of more than 700,000 square kilometers. So this prediction is actually an insult to those who truly love Sabah. The only reason why it can be hot for another 20 years is because outsiders will come in to Borneo, harvest out all the benefits and then leave. If they don't leave in 20 years time, they will start to pay just like the permanents. Where the business and finance ecology have been exploited, not to mention the environment.

How can we grow Borneo's property and leave a long term positive effect ?

1. Create MORE forestry reserve lands. this makes sure land is really limited.
2. Focus on ONE main theme - it should be along the nature's line ...
3. Form environmental alliance among Brunei, East Malaysia and Kalimantan.
4. This alliance has authoritative power over real estate development.
5. Beef up sea lines transport, bring in the industries

Then all the other developments can follow suit ...

So do we need that coal plant ? Well, I hate to ... but we do need to address the problem of water and power supply first.

If Borneo can be made into an eco-self-sustain-island, it can be the Eden for human races. Not only property will continue to rise forever but it could also be our last hope ...

And to iron out the whole architectural solutions in the next 5 years, we will need USD 20 billions now.

Saturday, December 26, 2009

Never buy a property that is fully sold ?


Joseph Tan is one of the most truthful guys who shared his property investment experience. Most property investors would properly brag about how superb property investment is, a smaller group who are willing to admit their failures would curse on it. But believe it or not, Joseph Tan's story actually covers the majority of how a property investor in this region would experience after some time i.e. from the 2nd to 5th property.

Basically he wasn't fully equipped with proper tools to start with but yet making great returns in his first 3 properties. However, the 4th one turned out to be a big lesson and he is sharing it with all. (details in Alan Tan's blog )

If disaster like this happened on the 4th or 5th property, it usually break even with previous earned profit or at worst became an expensive lesson. But for some who faced it on the 2nd or 3rd property, it usually crash their whole personal finance portfolio. Those who managed to stay alive had to start all over.

Most of his sharing are malpf compliant except one controversy point : Location, Location, Location ! For those who has followed malpf long enough, they know that malpf claims Location factor in property investment is just an overweight marketing topic by the developers. You can always jump on the developers band wagon to make some money but it wouldn't be a rock solid property investment strategy.

However, the main reason to mention his sharing is his 3rd point : Don't Buy a Shop in a Fully Sold complex - because - the developer will NO longer promote the property. Generally
  • if not many people are buying, its unlikely you will buy it (something must be wrong )
  • if many people are buying, its most likely you want to buy too ( must be an opportunity, don't miss it! )
And yet he shared his priceless advice ...

There are quite some insights to this sharing.
  • even such a successful business man like him still rely on developer to 'upkeep' the property/area.
  • if the area ( complex ) is no good, your property ( shop ) is no good too.
In any investment, once you are relying on others to make profit, your task is to make sure you join them as early as you could and leave right before they leave. Its NOT a rock solid investment, its more like a speculative exercise.

I am not sure if Joseph bought the shop in Galaxy Ampang but most other smaller shopping complexes in that area faced similar fate. However, some of the 1st batch buyers back then actually earned 15-20%. They jumped out before the developer did.

I know at least 2 private owners who are still keeping properties there and do not feel that bad about it. The biggest difference is they bought the shops for almost half of what other paid for back then.

I don't know if they had foreseen they had to wait 10-20 years but they did adhere to the first part of solid property investment strategy - always buy the property lower than its worth else its NOT a good buy.

Another specific factor on shopping complex is the floor level. The hottest property investment arena in Malaysia is Sungai Wang but once you go above 3rd floor, the value and worth drop drastically. For any non hot-spot shopping complex, looks no further than ground and 1st floor. Else you are not buying a shop, you are just buying a store room. The prices are assessed quite differently.

Friday, December 18, 2009

Loan is disadvantaged to Cash but Limited !

In an earlier article, a myth was broken where it says "getting loan will Decrease your liquidating options" so if you have the cash to buy the whole thing, you should go ahead and buy it and NOT getting a loan. Because once you get a loan, you will end up disposing your item Slower and get back Less worth - which is the opposite of liquidation.

That message has disturbed a lot of old friends who have been using loan successfully in their property investment. They have been borrowing loan in their investment for more than 10-20 years and almost always successful getting back a bigger return as a result of the loans. If loan is not a good thing or not liquidating, what has happened in the past 10-20 years, they just got lucky ?

Loan or any form of effective borrowing,
is a leverage tool.

Lets take a look at the same example used in last article; You have the option to buy an property for $100,000 and you could also get a loan where the interest is 5% for the next 10 years. Below spreadsheets show a few calculations;
The left most column in bold under "sell direct" mean if you bought with cash earlier and sell now, you would have get back this much money after the appreciation or depreciation.

The right most column in bold under "sell with loan" mean if you got the loan in the beginning, then this is what you get back in net after deducting the remaining capital.

The most important column in this article is the 2nd column from the left under "no loan - loan". It shows the difference of buying with cash vs buying with loan. If it is a positive number, it means buying with cash has an advantage earning or saving against buying with loan.
Below show 2 cases where the property could have appreciate or depreciate 10% a year ...

Case 1 : Item "appreciate" 10% a year


Case 2 : Item "depreciate" 10% a year


If you focus on the numbers in 2nd columns, they stay the same. It doesn't matter if your item increase or decrease in value, the differences between buy with cash and buy with loan are the same.

If your item appreciate, buying with loan will earn $5,000 less.
If your item depreciate, buying with loan will less $5,000 more.

It may still seems like a disadvantage to some readers up to here. But it actually is limiting the strategical cost of a transaction. No matter how the market goes, the person who got a loan will only lose $5,000 comparing to those who bought with cash earlier. In order words, the strategical cost of getting a loan is $5,000 for the 1st year.

You may also observe that this strategical cost is decreasing over the years. 2nd year the difference is less than $10,000 ( $5,000 x 2 ) and 3rd year is even less than $15,000 etc.

Limiting strategy cost no matter how the market goes is a very powerful situation in investment.


Sunday, October 18, 2009

Case Study : Property Investment Opportunities are Rare ?

Tammy achieves his financial freedom through property investment. Recently he bought over a property that looks too good to be true.
Purchase Price : $4 millions
Bank Loan : 100%
Loan Rate : 6%
Monthly Rental : $30,000
The property is sold at $ 3.8 millions but he lumps all the other fees in to make it $4 millions as his total cost. His net asset is way more than $4 millions so there is no problem to obtain that amount of bank loan. Loan interest is actually 5.XX but we round it up to 6% for this article. There are only 3 tenants, all are national and listed companies.

His monthly repayment is $23,982, fully paid by collected $30,000 rental, with a net cash flow of $6,018 every month. He didn't fork a single cent out because his bank is fully behind him in his deal.

Lucky him, just another rich guy gets richer, it has nothing to do with me, you may think ?

Well, every story is a lesson to someone. Its just a matter of what you get out of it. This opportunity did not just knock on his door and call it a deal with no reason.

It started around mid last year when the seller approached Tammy. Tammy made an offer but seller thought he had a better buyer and didn't take it. Then by last year end, seller took Tammy's offer but Tammy's offer has already expired. And Tammy met other better sellers. After beating around bushes and some silences, finally the deal is made this mid year. The whole process took around a year.

Can you imagine an opportunity of $6,000 net cash flow floating around in the market for one whole year and no one grab it like a crazy dog ? Well, that is the fact of life.
  • Many people want to buy it but not all of them have 4 millions
  • Many people do not qualify for a 4 millions loan
  • Some people CAN buy this but this may NOT be their only choice
  • Some people WANT to take this kind of opportunity but NEVER found this particular one!
  • Both seller and buyer may have personal preferences ... etc.
Yes the 1st two points may rule out almost 90% of the people, the Rich does get Richer easier. But that is because they have built their fortune faster and ahead of others. Not because it was taken for granted.

Don't forget this mentioned opportunity has been floating around publicly for one whole year, you and I didn't really know it until the deal was done. So it wasn't a matter of how rich other people are, its a matter of what you have done so that you can get what you really want.

Yes, again this is in Australia.

Other related articles

Wednesday, September 30, 2009

Guarantee Property Investment method


There are 2 embedded messages in this insurance article (1) and this financial freedom (2) talk.

(1) Build a passive income instead of thinking how to keep an active one
(2) You don't need Money if you have a solid finance plan

This article is about how to achieve both using property investment. But before we proceed, you must agree with a few pre-requisite concepts that were explained by this site before;
Income is a pre-requisite to Personal Finance but NOT a part of it, so amount of income is irrelevant to the strength of a personal finance plan.

Passive Income is achieved when you use 1/100 effort for an income.


Personal Finance is NOT the same as finance, Personal Finance is simple, straight forward and usually there is an obvious single best method.
Here are the 2 things to focus on; ( and these are strict requirements )
  1. Buy a property with Other People Money ( OPM )
  2. Rent the property out higher than repayment amount
By OPM this means using absolutely NO MONEY from your own pocket at all ! That's RIGHT ! You should get 100% or more loan in order to buy a property. If you can't get that, it only means 2 things; you don't have the right property OR you haven't used the right method yet. When you break this rule, you will also bear the consequences that this deal may NO longer be a personal finance tool.

If you borrow money, you have to pay it back. Your rental income must be more than your repayment amount. If you cannot ensure such a condition before the purchase, it is a NO DEAL ! When you break this rule, you will bear the consequences that this deal may NO longer be a passive income tool.

Remember this is all done at personal level, nothing fancy like real estate business world - which is earning much more but as an active income.

Impossible to get 100% loan and rent so high you say ? Then this is NOT your cup of tea. Period.

Both of these can be achieved by looking at only ONE factor - the actual buying price.

When you find a property, first identify its real worth. If it is a standard property then just refer to market price. Once you are convinced on the tenant-ability, then buy the property below its worth. For example,
A property worth $ 130,000 renting at $600 per month.

A 5% interest on $130,000 for 30 years may result a monthly repayment of $700 - which fail rule #2. Every month you are paying out $100 from your own pocket for someone else to use your property.

If you borrow less loan ie. $100,000 your monthly repayment is less than $550 which has positive monthly cash flow but this fails rule #1. In short, you have to fork out $30,000 now in order to get back $50 a month.
The rule of thumb is always buy a property 20-30% lower than its worth. So you buy above property at $ 91,000. Bank values the property at $130,000 and may finance you 80% or $100,000. After deducting all the fees, you may get $5,000 cash up front and then $50 every month. If the property price goes up in future, capital gain is to your advantage. If it goes the other way round, the risk is shared by the bank. A rock solid plan personal finance plan !

The lowest finance one should accept is 100% ( example above is 110% ) and the lowest net rental income is ZERO. It is ok if you have to pay some lawyer fee and stamp duty to buy a property. It is also ok to have your tenant pay your monthly repayment in full. Anything worse than that, is NOT a personal finance method.

But how often can you buy a rentable property 20-30% lower than its market price ? Not very often, not very often at all. There is only 1% chance of this will occur.

Can normal people like you and I get it ? Absolutely !

The funny thing is most property investors are Active Income chaser. They do NOT follow these rules strictly. Sometimes they don't care about 100% financing, other times they don't care about renting. Most of the time, they just have no patient. So they don't really bother this 1% of the pie. ( An example of property investment that is highly relying on capital gain alone )

Other non property investors simply DO NOT believe such things exist, hence they are not grabbing this pie neither.

In Kuala Lumpur I can be offered such opportunities 4-5 times a year.

Finding such opportunity should take more creativity than hard work. As of exactly how and all the methods of how to find them .... are whole new topics that are even more complicated than stock investment. Which is why not covered by malpf.

Stock investment is the highest level personal finance tool malpf promotes, Property investment is NOT within the 1Picture system. A good personal finance solution is straight forward, repeatable and practical. Property investment has too big a room to play about and most people get deviated and get into debt instead.

But if you follow this fundamental property investment method strictly, the most often said location factor is now secondary. Anyone anywhere can obtain unlimited passive income no matter how little money he has to start with.

Monday, June 29, 2009

Guest Post : Property as Passive Income

This is a guest post by Boon Ping. He is showing how one can turn property investment into long term passive income generator. This is actually a very common methods used in Australia, one of the world best property investment country. Altough recent down turn did affect Australia as well, but nevertheless still an area very active in this respect.

Do raise questions if you have any doubts in the comments area.


When we start in 2009, we put in $100K, buying an investment property at $500K with rental $25K per annum with loan amount $400K. Every year, we top up the loan based on its new market value to release equity(look at the Equity Released column on how much we get each year). We use the equity to cover any shorfall in mortgage repayment and also fund our income lifestyle. You see the equity balance keep increasing even though we keep spending.

You put in $100K, after 10 years you got $637K, 6x ROI. Remember this equity is tax free. What will you get after 10 years if you put in $100K into mutual fund? How much is left after tax?

Even we don't top up the loan each year, means the loan remain at $400K, the increase in rental is still sufficient to cover everything at the end, but this is not the strategy but just as worst case scenario.

This is with 1 property, what if you have 5, 10, etc.....

Basically the summary is in the excel file, noted that it's really a brief summary.

Assuming:
1) You start investing in a property worth $500K in 2009
2) Average annual capital growth = 10%
3) Average interest rate = 8.25%
4) Average inflation = 3%
5) Loan amount = 80% of market => Starting cost = $100K


Columns Definition:
Year => You know what it means
Value => Market value at that particular year
Original Loan => Loan amount when you first purchased the investment in 2009
Interest => Interest payable per annum based on ORIGINAL loan amount, ie loan amount x interest rate
Surplus => Rental - Interest - Maintenance
Equity => Different between current market value with ORIGINAL loan amount
New Loan => Loan amount based on 80% of the current market value
Equity Released => Different between current market value with NEW loan amount
Interest on New Loan = Interest payable per annum based on NEW loan amount
Maintenance => How much normally it need for maintenaning the property, eg council rates, management fee, repair, etc, 1% normally
Rental => Normally it's average 5% of the market value
Shortfall => How much you need to come out of own pocket money to pay for interest, maintenance after rental
Income => This is the passive income I am taking about, the income you need for living, spend, etc, increase each year
Total Spent Equity => How much equity that you spent
Equity Balance => Different between equity released and spent

I believe you sure got questions, feel free to fire back.

Friday, March 6, 2009

Conspiracy of Location, Location, Location !

Have you ever heard of someone telling you the 3 most important things in property investment ?  Then he repeated saying the word "Location" 3 times ?

Well I have!  I have heard that so many times since so young that it was imprinted in my head without proper judgment.  You know, say the lie 100 times and it would become the truth. 
A lot of people got into real estate and their first few years ended up paying high lesson fee TOTALLY WASTED on this so call principal Location, Location, Location !  A Conspiracy !

First of all, have you ever heard seller saying the location is not that good ?  And therefore they are selling the property at a lower cost ?  - - -  N O ! - - -  Every location "can be" a good location.

Do you know that sometimes property at the right side cost much higher than the left side even though at the same location, same build up, same type of buildings ?  - - - Yeap !  You Bet ! - - - Usually by 2 different developers.

Why is there always a few units in the Golden Location not able to sell out or always make a lost in resell ?

If Location is really the Number 1 factor in property investment, all the above should not happen at all.

This miss conception is originated from the developers.  Whenever developer launches new projects, they will make a big deal about the location.  No doubt at the time they promote the project, the location could be a great place.  However, eventually whatever highways promised earlier may not be built later.  Sometimes even after the high way is built, the effect is negative rather than value increase.

Even if nothing happens to the original location, but when the same developer is launching another new project, guess which is the better location ?  Yeap !  The new one !  Not your older location.

Hence, this location factor is purely a speculation in real estate investment.

Like any investment, what really matter is its real worth and its current price.  If the price is lower than its worth, its a good buy.  Else its a good bye !

No doubt location is a factor, but it is NOT an important factor at all !  Most of the times it is merely a Personal Flavor factor.


Prime location property is easier to rent and sell out but more expensive and usually not available.

Secondary location is cheaper and readily available but harder to rent or resell out.

So give and take, the pros and cons of different location even out each other and do you need to compare properties between two locations ? - - N O ! - -  Not really. 

Different locations carry different characteristics and require different investment methodology.  But the principals remain the same ;

1.  Identify, calculate and verify a property's real worth
2.  wait and buy the property at big discount
3.  ensure continuous net cash inflow ie. Rental - Repayment = positive
4.  appoint experience management or agents at that particular location

So if you purely treat real estate as an investment, you don't really need to worry too much about the location as long as the 4 steps above are strongly adhered to.


There are only 2 decisions that may be affected by location ;

1.  Get a location near you or a location that you love personally.  That way, should the investment goes south, you may temporary enjoy the non tangible personal qualitative returns - a personal flavor as mentioned above.

2.  Location can be the reason NOT to buy a property, but it should NEVER be the reason you put money into it.

Blogged with the Flock Browser

Wednesday, November 12, 2008

Property as an investment

Just a reminder that Car Loan interest rate is about 1.9X more than the House Loan.  Meaning a 3% car loan is almost as high as a 6% house loan.  Think again if you think car loan has a lower interest rate.  (click here to read more).

The fundamental of investing in property is not much different than buying a business to earn you passive income.  However, the nature of brick and mortal business is an Active Income generator, not a passive one.


VS


So you would need to be extra careful when using property as your finance tool to gain "Passive Income".

In simplest term, you HAVE TO make sure
  1. you can rent your property out to fully pay for the monthly loan repayment
  2. you budget in the fee you pay for professional to maintain your property including
Lawyer
Real Estate agents
Renovation
Interior Design if needed etc.
Without these 2, you cann't start property investment at all.  With this, there is no guarantee you can win big yet but at least you would at least pay less to learn the lessons.


Wednesday, October 29, 2008

Stock vs Gold vs Property

Below I share some historical trends for Stock Market, Gold and Property.  They are not directly correlated but each is good enough to represend some form of global historical trend.  So they are good enough as an overview and for layman entry level comparison.
Stock market
Gold
Comparison 1 - 1975 to now

Gold has earned 3.5x
Stock market 8x
Property 10.7x

Comparison 2 - origin to now
Gold 28x ( since 1930 )
Stock 800x  ( since 1944 )
Property  16x ( since 1960 )

normalize above return by the difference in years become
Gold  35.9% 
Stock  1250%
Property   33.33% 

However, stock starts at 1 in 1929 and therefore give too large a gap in above comparison.  So I decide to use 1960 where stock index is at 20.  If I use this 20(1960) instead of 1 (1944 ) for stock, then I get

Gold  35.9% 
Stock  83.33%
Property   33.33% 

Gold Trend in Longer History

Comparison 3 - lowest valley to highest peak

Gold's peak at 1000 at 2007
Property peak at 181 at 1996
Stock dip to 1 in 1984

Gold  40x ( min 1923 max 2007 )
Stock  800x  ( min 1984 max 2008 )
Property  22.6x ( min 1960 max 1996 )

Gold  47.62% 
Stock  2352.94%
Property    62.85% 

Like wise stock's number is too crazy so I use 20 instead of 1 for stock and result this:

Gold  47.62% 
Stock  117.65%
Property    62.85% 

==================
I am not too excited about any of these return rate because past performance does not guarantee future profits.  However, after looking at these graph I am very excited because I think I see some repeated trends in stock market.  It seems QUITE predictable from this graph alone.  However, I cannot figure out any "Patterns" for Gold and Property.  Therefore I am quite sure what I need to do for stock investment, but not the others.

==================

so my final word on this comparison is you should only read this for 'fun' or at most a guide only.  Remember that global trend and all these 'overall' figure does NOT really affect you.  Because you will NEVER buy the whole world.  You will only buy a few stocks or just 1 or 2 properties.  The unique buys you make for yourself determine the REAL profit for your very self.  Global trend does NOT mean you have no chance to out beat it.